Walk through any insurance operations queue and you’ll find a familiar pattern. A large share of the items are routine: an address change, a vehicle swap, a renewal with no material changes, a small claim with a clean invoice and clear coverage. They sit in the same queue as complex exceptions, wait for the same people, and receive the same manual review.
That’s the core inefficiency straight-through processing addresses. The goal isn’t to automate judgment. It’s to stop spending judgment on work that doesn’t need it, so clean work flows and people focus where they add value.
This post covers how automated validation works, where straight-through approvals fit, and how to design controls that make operations, compliance, and auditors comfortable.
Why routine work gets stuck
Routine transactions get stuck for three reasons:
- Data arrives unstructured. Requests come by email, portal free text, or PDF. Someone has to read them and key the details.
- Validation is manual. Even simple checks — is the policy active, is the requester authorized, is the change within guidelines — are done by a person looking at multiple screens.
- One queue for everything. Without upfront triage, a two-minute change waits behind a two-hour exception.
The result is longer turnaround for customers and brokers, higher handling costs, and experienced staff spending their day on keystrokes.
What automated validation does
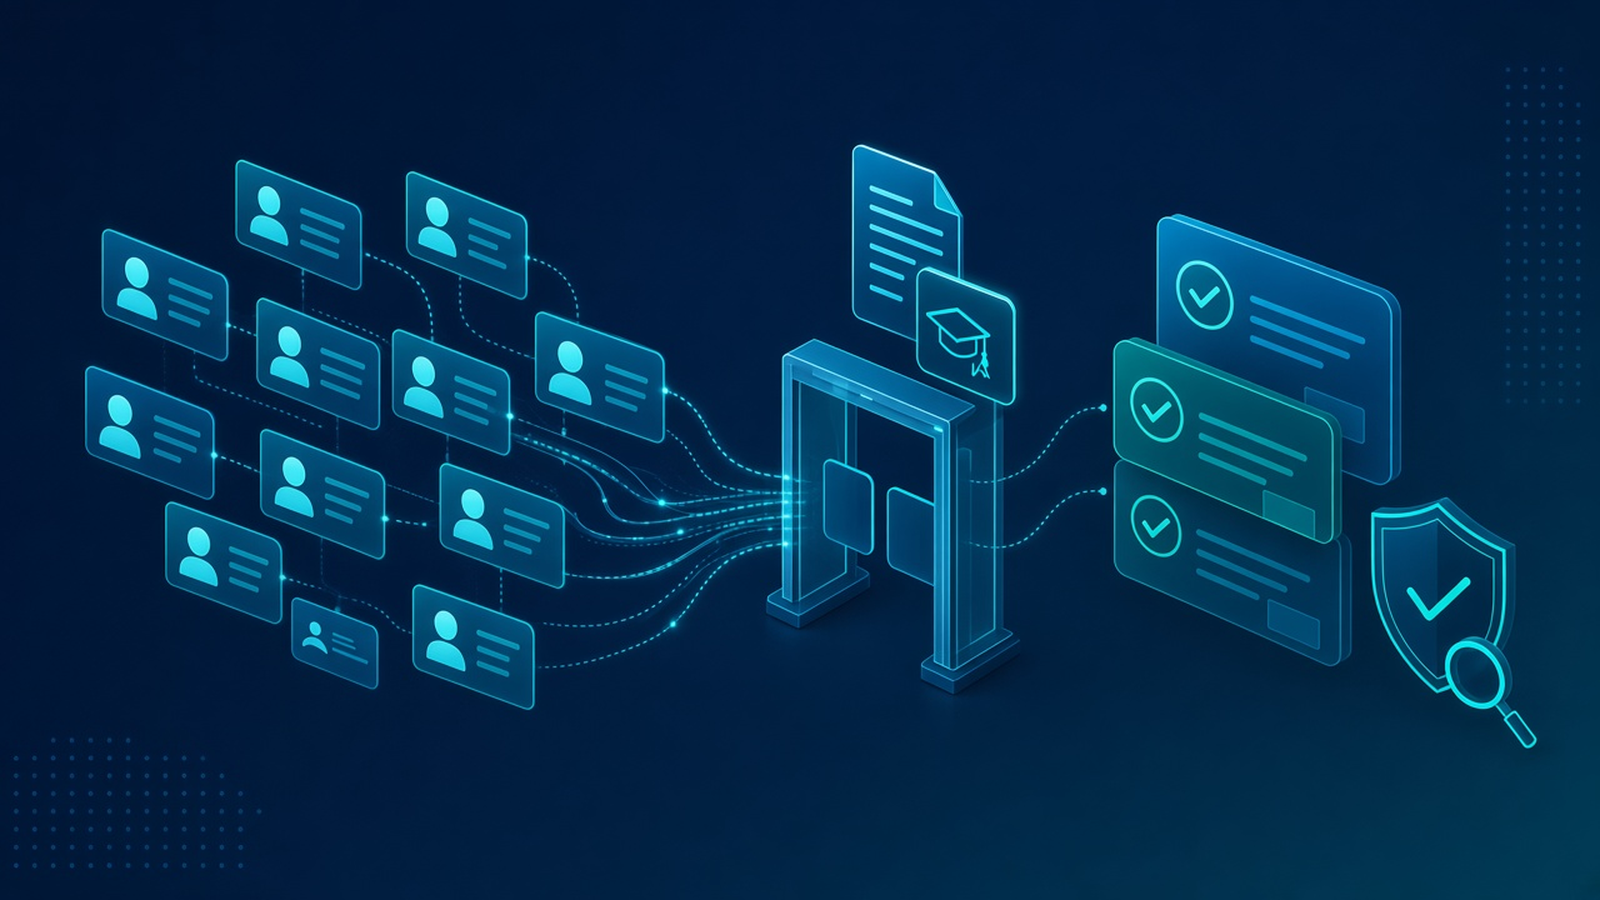
Automated validation applies the same checks a person would, consistently and instantly, to every incoming item:
- Identity and authority. Is the requester the policyholder, an authorized agent, or a broker of record?
- Policy status. Is the policy in force, paid, and not under cancellation or claim restriction?
- Data completeness. Are all required fields present and well-formed?
- Business rules. Is the change within underwriting guidelines — for example, a vehicle within acceptable classes, a sum insured change below a threshold, a location within appetite?
- Consistency. Do values match across documents and systems?
- Risk signals. Any fraud indicators, recent claims, or watchlist matches that require review?
Each check produces a pass, fail, or needs-review result, with the reason recorded.
From validation to straight-through approval
When every check passes and the transaction type is pre-approved for straight-through handling, the system completes it: updates the policy or claim, generates documents, and notifies the customer or broker. When any check fails or flags, the item goes to a person with the specific issue highlighted.
Good candidates for straight-through approval share a profile:
- High volume
- Clear, documented rules
- Low financial or regulatory consequence per item
- Easy reversal if something goes wrong
Common examples include:
- Personal lines endorsements such as address changes, driver additions within rules, or vehicle replacements.
- Clean renewals with no material change and acceptable loss history.
- Certificates of insurance for standard requests.
- Small claims below a threshold with verified coverage, consistent documentation, and no red flags.
- Billing changes like payment method updates.
Complex commercial changes, large claims, and anything requiring coverage interpretation stay with people.
Designing the controls
Straight-through processing only works if the business trusts it. That trust comes from controls designed upfront.
Explicit, versioned rules
Every rule that permits straight-through handling should be documented, owned by a named business leader, and versioned. When a rule changes, the change is approved and recorded like any other underwriting or claims guideline.
Thresholds and limits
Set conservative thresholds to start — for example, low claim amounts or limited endorsement types — and widen them based on measured results. Include volume limits so an unexpected surge triggers review.
Sampling and quality assurance
Review a random sample of straight-through transactions on a regular schedule. Compare outcomes with what a person would have decided. Track the error rate and adjust rules accordingly. No automated process is error-free; sampling is how you find and fix the errors that slip through.
Clear reversal paths
Every automated action should be reversible, with a documented process for correcting mistakes and notifying affected customers.
Full audit trail
For every transaction, record which checks ran, their results, the rule version applied, and the outcome. Auditors and regulators should be able to see exactly why an item was approved without human review.
Measuring success
Track a focused set of metrics:
- Straight-through rate by transaction type
- Turnaround time for straight-through versus manual items
- Exception rate and top exception reasons
- QA error rate on sampled straight-through items
- Staff time redeployed to complex work
The exception reasons are particularly valuable. They show where data quality, rule clarity, or upstream processes need work. Often, fixing a single upstream issue — like a portal field that allows invalid entries — raises the straight-through rate significantly.
Common pitfalls
- Starting too broad. Trying to automate every transaction type at once spreads effort thin and raises risk. Start with one or two.
- Rules nobody owns. If IT owns the rules, the business won’t trust them. Business owners must approve and maintain them.
- No feedback loop. Without regular review of exceptions and errors, rules drift out of date.
- Ignoring the people. Staff need to understand that straight-through processing removes repetitive work, not their roles. Involve them in defining rules; they know the edge cases.
A phased approach
- Map transaction types by volume and complexity. Identify the top candidates.
- Document current rules with the people who apply them today.
- Automate validation first, with every item still reviewed by a person. Measure how often the system’s pass/fail matches human judgment.
- Enable straight-through approval for the highest-agreement transaction types, with sampling in place.
- Expand thresholds and transaction types as evidence accumulates.
What customers and brokers notice
The visible result of straight-through processing is simple: requests that used to take days are completed in minutes, with confirmation documents arriving immediately. Brokers stop chasing status on routine changes, and service teams field fewer follow-up calls. Those indirect savings, fewer status inquiries and less rework, often add meaningfully to the direct handling-time reduction and are worth measuring alongside it.
The bottom line
Most insurance work is routine, and routine work shouldn’t wait. Automated validation and straight-through approvals let clean transactions complete in minutes while giving people more time for the exceptions that need them. With documented rules, sampling, and a full audit trail, it’s a control improvement as much as an efficiency gain.
Find out which of your transactions could flow straight through. The Aketud Insurance AI Workflow Review maps your highest-volume transactions and identifies where automated validation would pay back first.